
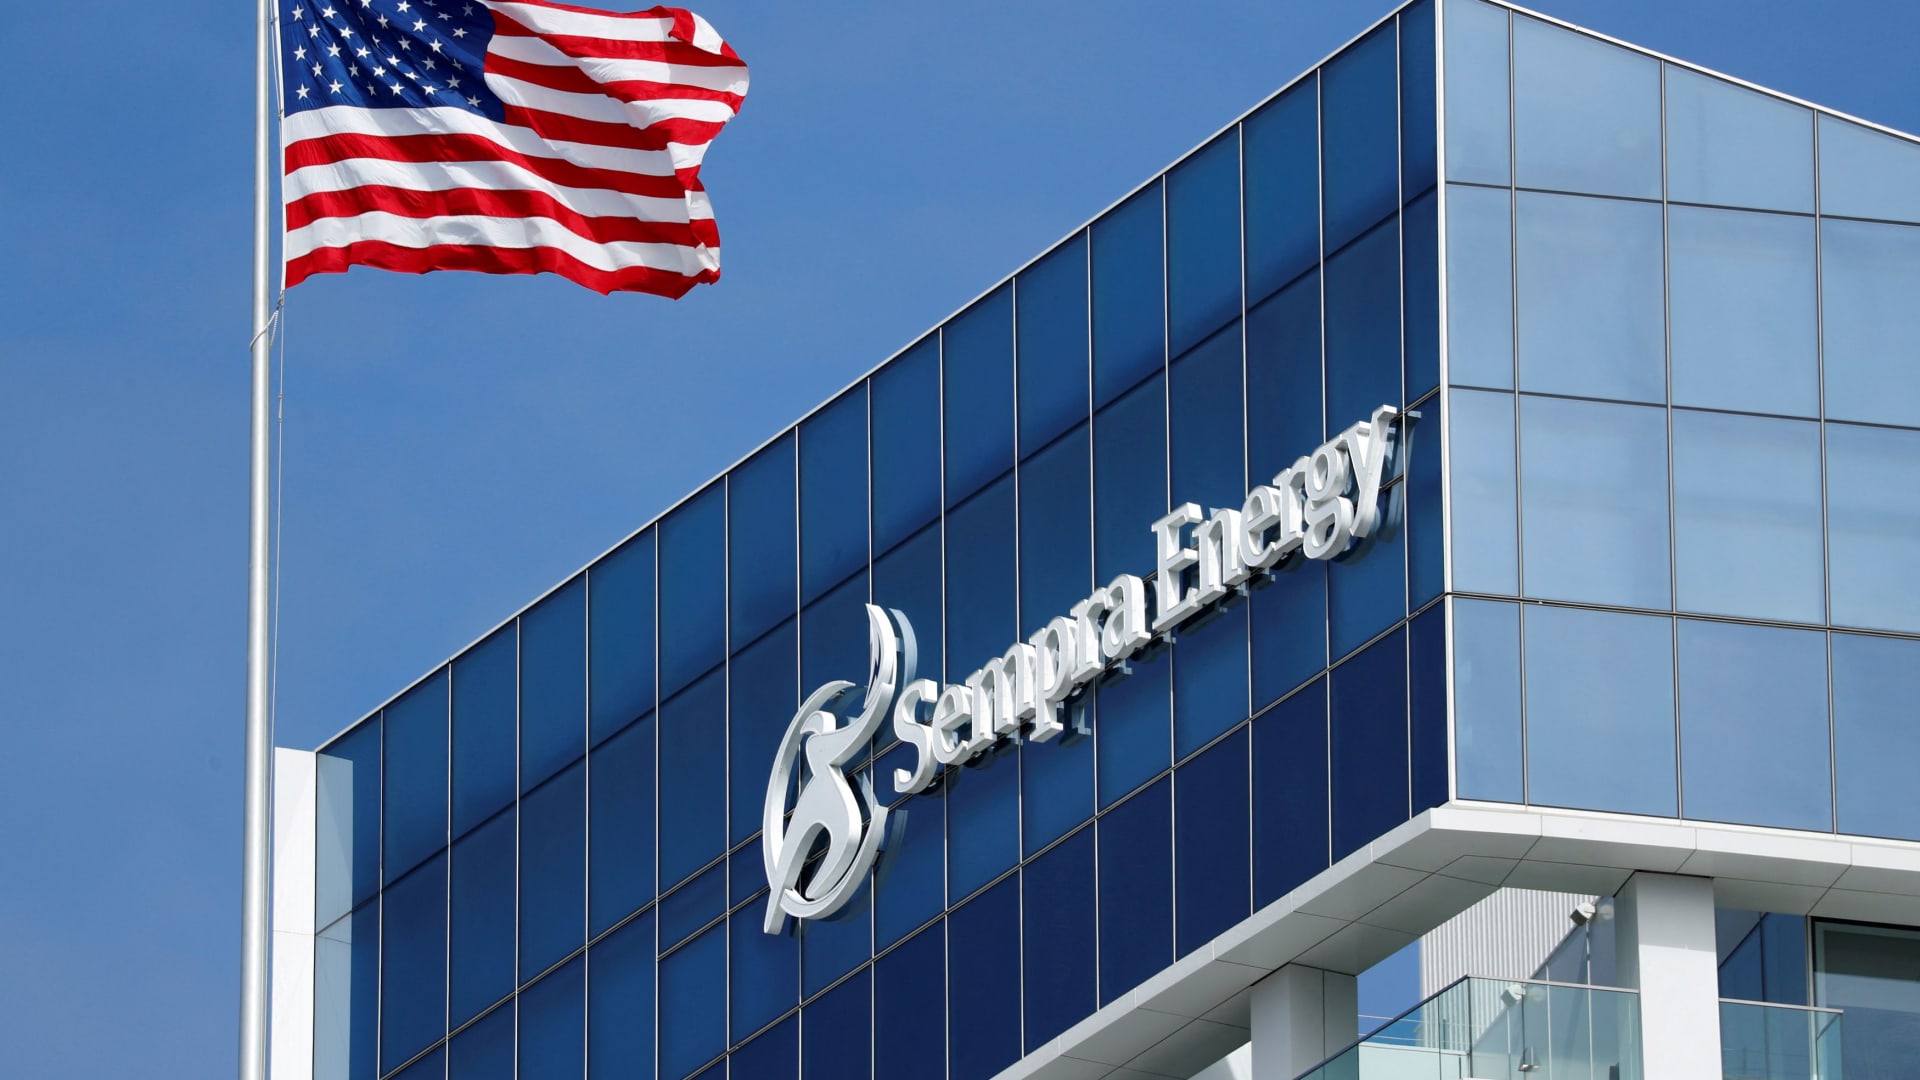
The Sempra Energy headquarters is pictured in downtown San Diego, California, on May 17, 2018.
Mike Blake | Reuters
Dividend-paying stocks can enhance portfolio returns by providing a steady income stream to investors and the potential for capital appreciation. Several investors seek exposure to dividend stocks in a volatile backdrop to ensure stable income.
In this regard, recommendations of top Wall Street analysts can help shortlist attractive dividend stocks, backed by strong financials and cash flows to support consistent dividend payments.
Here are three dividend-paying stocks that are highlighted by Wall Street’s top pros, as tracked by TipRanks, a platform that ranks analysts based on their past performance.
Energy Transfer
Energy Transfer (ET) is a diversified midstream energy company with about 140,000 miles of pipelines and associated energy infrastructure in 44 states. The company made a quarterly cash distribution of 34 cents per common unit for the second quarter of 2026. At an annualized payment of $1.36 per common unit, ET offers a yield of 6.3%.
Recently, JPMorgan analyst Jeremy Tonet reiterated a buy rating on Energy Transfer stock and slightly raised his price target to $25 from $24. The analyst noted that the company delivered a strong Q2 beat across all key metrics.
Tonet highlighted that Energy Transfer raised its 2026 adjusted EBITDA guidance to $18.8 billion-$19.1 billion from $18.2 billion-$18.6 billion, reflecting robust base results and cost optimization. The 5-star analyst added that the company “tightened” its capex to $5.6 billion–$5.9 billion and expects capex above $5 billion annually through 2029, given solid opportunities.
About the Hugh Brinson pipeline, Tonet noted Phase 1 (1.5 bcfd) reaching full capacity by September 1 and Phase II capacity (0.7 bcfd) going online by Q1 2027. The analyst also noted completion of a 14-mile Hugh Brinson lateral in Abilene, Texas, and final stages of talks for an additional 250 mmcfd of Oklahoma power plant demand.
“All in, we see ET well positioned to continue capitalizing on organic growth opportunities across the value chain,” said Tonet.
Tonet ranks No. 922 among more than 12,500 analysts tracked by TipRanks. His ratings have been profitable 57% of the time, delivering an average return of 9%. See Energy Transfer Financials on TipRanks.
Permian Resources
This week’s second dividend pick is independent oil and natural gas company Permian Resources (PR). The company declared a base dividend of $0.16 per share for the third quarter, payable on September 30, 2026. At an annualized dividend of $0.64 per share, PR offers a yield of about 2.7%.
Recently, Goldman Sachs analyst Neil Mehta reiterated a buy rating on Permian Resources stock and increased his price target to $27 from $22, citing an improved outlook on oil production growth and operational efficiencies.
The 5-star analyst noted that while PR stock has outperformed its peers so far in 2026, he sees further upside. Mehta is confident about the company’s operational improvements and ability to deliver incremental free cash flow per share through the strategic ground game program. He added that the program has completed about $1.05 billion in bolt-on deals this year (as of August 5).
“We see the continued success of PR’s ground game as constructive toward future inventory replenishment and increasing working interest over time,” said Mehta.
The analyst also emphasized Permian Resources’ solid track record of generating growth in free cash flow (FCF) per share. Mehta expects the company’s free cash flow per share to grow at a 20% CAGR (compound annual growth rate) from 2025–2028.
Mehta ranks No. 401 among more than 12,500 analysts tracked by TipRanks. His ratings have been successful 64% of the time, delivering an average return of 12.8%. See Permian Resources Statistics on TipRanks.
Sempra Energy
Moving on to Sempra Energy (SRE), a utility holding company. Earlier this month, the company declared a quarterly dividend of $0.6575 per share, payable on October 15. At an annualized dividend of $2.63 per share, SRE stock offers a yield of about 3.1%.
Recently, Jefferies analyst Julien Dumoulin-Smith upgraded SRE stock to Buy from Hold but slightly lowered the price target to $97 from $101. The 5-star analyst noted that Sempra stock is trading at a price/earnings multiple that is 14% below its electric peers due to concerns about Texas transmission capital expenditure and the failure of California legislation.
Smith noted that the derating of weaker California peers PG&E (PCG) and Edison International (EIX) is weighing on the sum-of-the-parts (SOTP) valuation but is becoming less relevant given their materially higher fire risk compared to Sempra Energy.
Furthermore, Smith expects Sempra Energy’s Texas capex plan to stay in place despite the opposition to transmission and data centers, though delays to 765-kV projects are likely. While a full recovery for SRE stock will need a clearer outcome from the Texas legislative session, Smith believes that the stock may already be an early opportunity for patient investors.
“We are early on the upgrade but see limited downside at current levels as the market is pricing in little transmission upside,” said Smith.
Smith ranks No. 945 among more than 12,500 analysts tracked by TipRanks. His ratings have been profitable 61% of the time, delivering an average return of 8.2%. See Sempra ETF Exposure on TipRanks.
