
Stay informed with free updates
Simply sign up to the Property sector myFT Digest — delivered directly to your inbox.
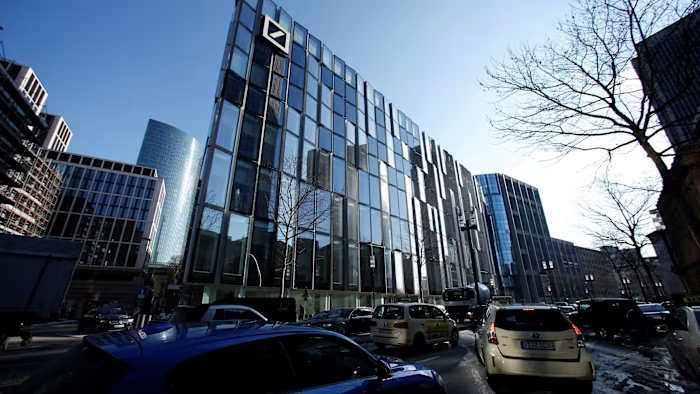
Deutsche Bank’s asset manager DWS is considering emergency measures to stave off a liquidity crunch at three of its German property funds, as an investor exodus puts mounting pressure on the country’s €100bn-plus property fund industry.
Three DWS “Grundbesitz” open-ended funds have collectively paid out €6bn to investors — around half of their assets under management — since 2022, forcing them to sell properties worth €4.5bn and pushing their borrowing towards statutory limits, fund disclosures show.
DWS is now considering limiting redemptions or imposing penalty fees on departing investors under new EU rules, according to people familiar with the matter.
The pressure on DWS’s German funds comes as the asset manager is winding down a smaller US retail property vehicle. RREEF Property Trust, which had a net asset value of $203mn at the end of June, plans to liquidate after suffering persistent redemptions and struggling to attract new capital.
DWS is among the hardest hit by a sell-off in an investment product long popular with Germany’s risk-averse savers. Investors have pulled a net €17.3bn from German-domiciled open-ended retail property funds since the beginning of 2024, reducing the industry’s assets under management to €107bn by the end of July, according to Bundesbank data.
BaFin, Germany’s financial regulator, told the FT that outflows remained high and warned that further funds could suspend redemptions. It said the withdrawals did not pose an acute systemic threat to the wider financial system but represented a “structural risk” to the sector unless conditions in commercial-property markets improved.
The withdrawals have reversed years of growth during the era of ultra-low interest rates, when the funds were widely used as an alternative to bank deposits and attracted savers with returns of 2 to 3 per cent. Higher deposit rates since 2022 have removed much of that advantage.
“The first products were launched in 1970 and were often presented as, look, this is basically the only product that can generate a positive result in every market environment,” said Christian Bäcker, DWS’s head of European real estate portfolio management for retail clients. “That held true for most products for a very, very long time . . . and then reality caught up with the products a little.”
The funds predominantly invest in illiquid commercial property. More than half of their assets are offices, which have suffered a years-long downturn. Raising cash for departing investors can therefore require selling buildings into a market suffering from weak demand and higher financing costs.
“The more this selling pressure persists, and the more redemptions the funds have, the more properties they have to sell in the current market environment, accompanied by reductions in valuations,” said Sonja Knorr, an analyst at German fund rating company Scope.
Scope forecasts average property fund returns of between minus 0.5 per cent and minus 1.5 per cent by the end of 2026.
Five smaller German open-ended retail property funds have already suspended redemptions or entered liquidation this year. Investors generally have to give 12 months’ irrevocable notice before withdrawing their money — a safeguard introduced after the 2008 financial crisis, when 18 German open-ended property funds with €26bn in assets were closed to redemptions and subsequently wound down, according to Scope.
The notice period gives managers visibility over future withdrawals, but property sales can now take just as long, leaving them vulnerable when transactions fall through.
Investors unwilling to wait 12 months can sell their fund units on the secondary market, where some large funds currently trade at discounts of up to 38 per cent to their official redemption prices. Part of the gap reflects the price investors pay for immediate liquidity, but consumer advocates argue it also raises questions about official property valuations.

The turmoil has also revived debate over how the products were sold. Deutsche put DWS’s property funds on “hold” around 2023, in effect stopping new sales through its main distribution channel, according to people familiar with the matter. Deutsche declined to comment.
“The products are closely intertwined with commission-driven financial distribution,” said Niels Nauhauser of consumer organisation Verbraucherzentrale Baden-Württemberg. Investors have typically paid upfront charges of about 5 per cent, while some products report annual ongoing costs of as much as 3 per cent.
“They were also sold to investors who did not want a long-term investment and who were looking for safety.”
Many funds historically received scores of one or two on the EU’s seven-point risk scale. “In some cases, bond funds were assigned a higher risk category than property funds,” Nauhauser said. “That gives a misleading impression of the actual risks. Property isn’t safe — you just don’t see the changes in value immediately.”
Fund managers say the scores are determined by EU rules based largely on historical volatility. BaFin is pushing for changes that would result in higher risk ratings, while an EU court ruling on the methodology is pending.
“I think many people have an expectation when it comes to property that you can’t lose money,” DWS’s Bäcker said. “Of course you can lose money. You can lose money with anything.”
