
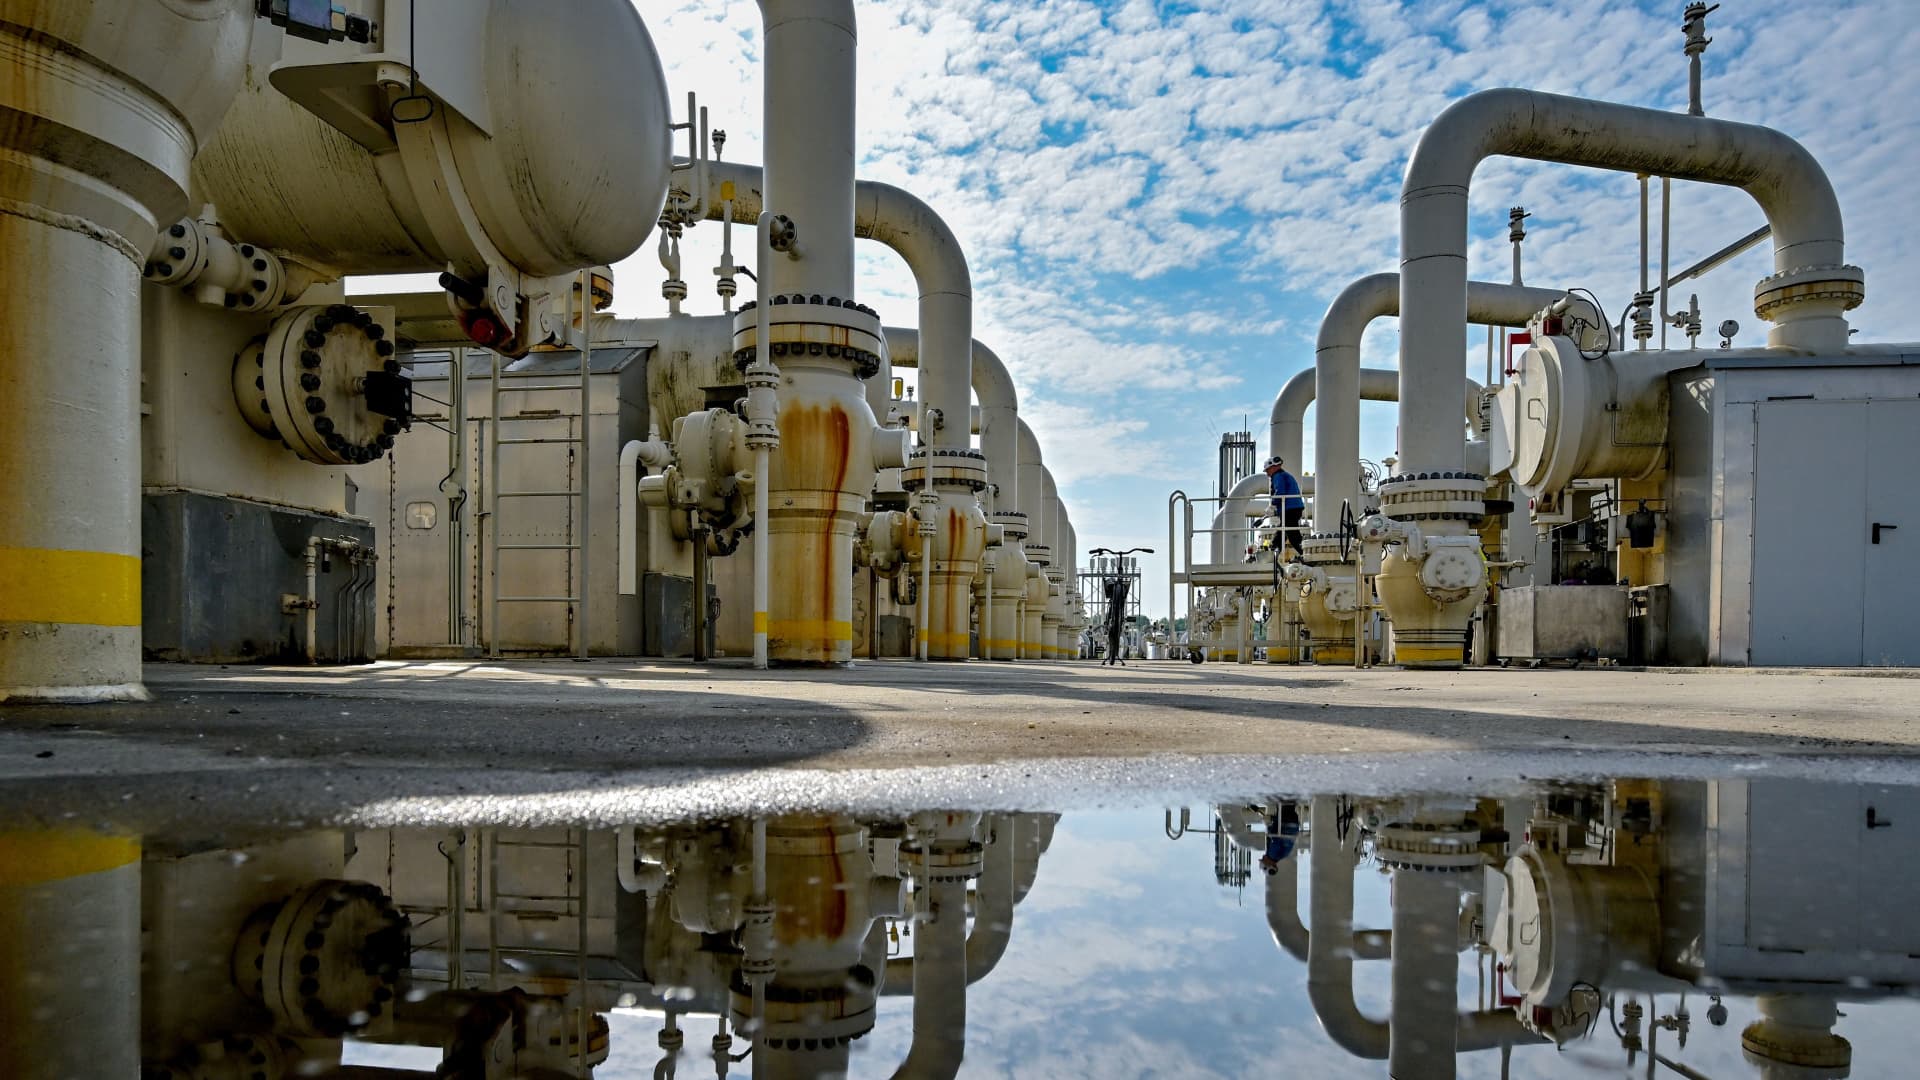
European natural gas prices continue to rise as the continent’s stocks are depleted to record lows, fueling fresh fears of a looming winter price shock.
Dutch Title Transfer Facility (TTF) futures for December delivery were last seen up 4.9% higher at 102.78 euros ($115) per megawatt-hour on Friday, having exceeded 100 euros on Wednesday.
That puts Europe’s benchmark gas contract up about 36% for the month, and 256% for the year, according to Trading Economics data.
Friday’s jump puts Europe’s gas prices at their highest level in almost four years, when the continent was grappling with soaring energy costs caused by Russia’s invasion of Ukraine. Dutch TTF futures hit 139 euros per MWh on Dec. 5, 2022, having earlier spiked to 339 euros per MWh in August that year.
WisdomTree European Natural Gas ETP.
Winter temperature fears loom over Europe’s gas supplies
Rising prices come amid renewed warnings that the continent is ill-prepared for a colder winter.
Natural gas storage in Europe now stands at about 75%, its lowest seasonal level since recordkeeping began in 2011, as disruptions to shipping through the Strait of Hormuz have hampered efforts to replenish stocks over the summer.
With stocks depleted, a colder winter could push European energy prices, already up 170% this year, even higher, BlackRock analysts said in a note Oct. 27. Natural gas makes up about one-sixth of the EU’s energy generation.
Europe bets on unseasonable warmth
Peter Taylor, head of commodity desk strategy at Macquarie, said Europe is essentially betting on a warm winter, a stance tied to the El Niño climate event. That’s despite the U.K. and Europe having often seen some of the coldest winter snaps during El Niño events, Taylor explained.
“The danger is that we have a mild or cold winter. We’re in a situation where we actually need quite a warm winter to make it through unscathed,” Taylor told media, including CNBC, at an October commodities roundtable.
“We’re in a situation now where, if we do get that cold weather, we’re potentially seeing Europe compete with Asia for molecules, and that has potentially a lot of [price] upside.”
Europe and much of Asia are more heavily exposed to potential gas price shocks than the U.S., which benefits from both domestic shale and LNG production.
“The energy shock has uneven effects,” BlackRock said. “We estimate it’s reduced GDP by about 0.5% in Europe, compared with just 0.1% in the U.S. Those differences could become even more pronounced.”
