
Unlock the Editor’s Digest for free
Roula Khalaf, Editor of the FT, selects her favourite stories in this weekly newsletter.
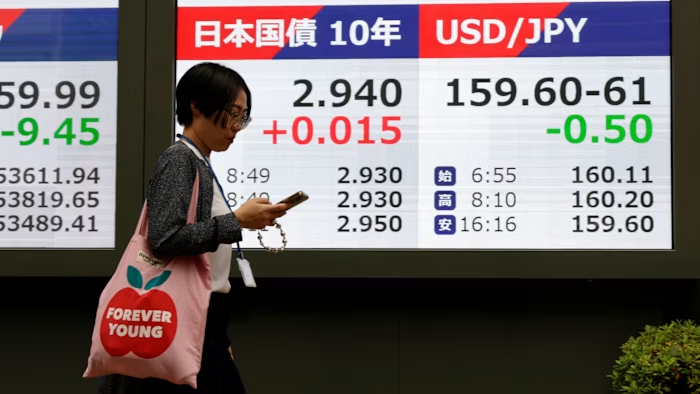
For bond traders, the summer lull in workloads never quite arrived. On Tuesday, the months-long rollercoaster sell-off of global sovereign debt intensified as yields in advanced economies hit worrying new highs. In Japan and the UK, long-term government borrowing costs hit multi-decade records; the 10-year US Treasury yield — a global benchmark for debt — surged to its highest since January 2025.
There are several explanations for the latest rout. For starters, a flare-up in the Iran war over recent days renewed fears that central banks will need to raise rates to combat higher energy prices. On Friday at the Jackson Hole symposium, Federal Reserve chair Kevin Warsh was unexpectedly hawkish. Competing issuance by companies powering the AI boom and the shift towards more short-termist investors in sovereign bonds has contributed to upward pressure on borrowing costs too. But the underlying cause is far more prosaic: governments are spending beyond their means.
The average ratio of public debt to GDP across advanced economies has settled comfortably above 100 per cent since the pandemic. The trajectory now appears to be worsening. Shocks to energy and food prices have added to existing spending pressures on governments from ageing populations and rising defence commitments.
A lack of fiscal discipline has made matters worse. Britain last year shied away from reforms to its generous benefits system. In Japan Prime Minister Sanae Takaichi is pursuing an expansionary fiscal policy just as sustained inflationary pressures appear to be returning. In the US, tax cuts in President Donald Trump’s One Big Beautiful Bill Act have added to the country’s ballooning debt problem.
As higher borrowing costs add to already bloated sovereign debt piles, the prospect of regular, disorderly bond sell-offs is only set to rise. Political leaders worry about a political backlash from substantive spending cuts or tax increases. Meanwhile, any AI-led revival in productivity growth and hence tax revenues will take time to materialise, and central banks are limited in their ability to tame inflationary pressures emanating from global supply shocks.
In turn, as recent research by the IMF highlights, there is a growing risk that governments will resort to financial repression, including direct interventions in bond markets to keep interest rates artificially low. Investors accused US Treasury secretary Scott Bessent of this when he announced a plan to increase buybacks of long-dated government debt last month. (A desire to protect Treasuries has also been behind his recent efforts to prop up the yen.) Other potential tools include changes to bank capital rules, requiring domestic institutions to hold more government debt and even capital controls.
Financial engineering can at best buy time for governments, but only at the risk of destabilising bond markets even more. Efforts to hold down rates punish savers, complicate the job of central bankers and, crucially, drown out vital price signals and undermine trust in public debt. Whatever tools they use, finance ministries risk fighting wasteful and losing battles with globally interconnected capital markets.
Governments should resist the temptation for shortcuts. The most sustainable way to reduce the risk of market ructions is to listen to the signals coming from bond investors, not to ignore or suppress them. That means tackling rising welfare and pension costs head-on and resisting giveaways or tax cuts without credible funding plans. Avoiding political pain today will not make the problem disappear, it only stores up instability in bond markets that could force more painful economic choices tomorrow.
