
Unlock the Editor’s Digest for free
Roula Khalaf, Editor of the FT, selects her favourite stories in this weekly newsletter.
The writer is group chief executive of Nesta, a UK innovation charity
“Take back control”, once the slogan for leaving the EU, is now the animating idea of the Burnham government. Nationalising Thames Water or regulating local bus networks have been mooted as ways of protecting customers from rising costs and poor service. But state action can also create wealth. As India and China have shown, public control can stimulate market dynamism rather than replace it, nurturing world-class industries in turn.
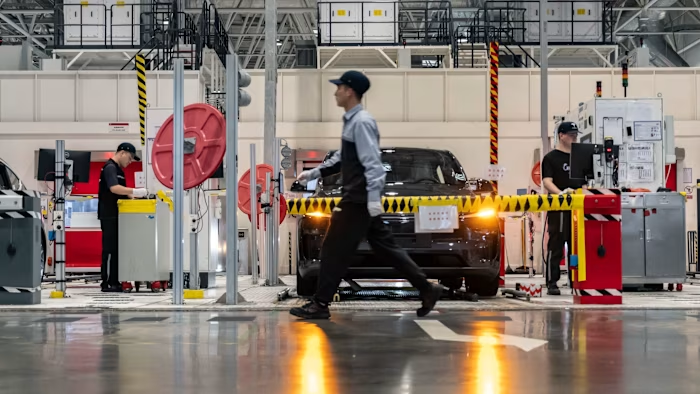
Last year, the Chinese car company BYD overtook Tesla and sold more electric vehicles globally than any other company. The market for their cars would not have existed without state regulation, subsidies and the building of charging infrastructure. But rather than anointing BYD as a national champion, the Chinese state also created a fierce technology race, with competition driving innovation. It was this unusual combination of muscular state action to drive demand, alongside a Darwinian selection mechanism, that forged a world-beating company.
India’s digital revolution also shows how government intervention can drive innovation. Today, when you buy vegetables from a street vendor, you pay by scanning a QR code — the vendor pays no fee to anyone. Rather than allowing payments to be captured by Visa or Mastercard, the government built digital public infrastructure. Dozens of apps now compete fiercely on these digital “rails”, carrying more than half a billion transactions every day. No platform has excessive market power, so no intermediary can squeeze consumers or merchants.
What are the lessons from these experiments? First, public control need not be a defensive project confined to old industries. It is more relevant when it comes to managing big transitions, from stewarding AI to electrifying the economy.
Second, it requires system architects. We need people with deep technical expertise in senior positions, rather than Whitehall generalists. These individuals need to sit within durable institutions capable of setting the direction for whole sectors, working closely with mayoral strategic authorities.
Even where the UK has created a system architect role — the National Energy System Operator, for example — decision-making authority is fragmented across multiple independent state institutions, from Great British Energy and the National Wealth Fund to Ofgem.
Third, the system architects need the power and resources to drive change. Big transitions are stymied by chicken-and-egg co-ordination problems. For example, EVs rely on charging infrastructure, but who builds it when the demand is uncertain? The government’s answer — the zero-emission vehicle mandate, alongside capital grants for infrastructure — de-risked investment in this area. But outside of energy, interventions lack the same heft.
Fourth, India and China show that public control can enhance market competition. Much better to set a direction for a market and let a winner emerge than for the state to pick one.
Finally, we should look again at finance. Private investors in monopoly assets are often paid for a risk the public bears anyway. Regulators, as the water industry has shown, are being consistently outfoxed. Full state ownership may serve us better. Where the state is involved in shaping a market, and reducing risk through long-term contracts, it should own part of the upside — for example, through equity stakes.
For the Brexiters, and now Andy Burnham, “take back control” has been clothed in nostalgia. Grievance is a place to start, not to govern from. The lessons of Bengaluru and Shenzhen are that a modern state can do more than reclaim the industries of the past — it can create markets and drive innovation. That is the version of control worth taking back.
