
Don’t touch your capital! That is a key tenet of income investing. In its purest form, this involves living on payouts generated by a nest egg you leave intact.
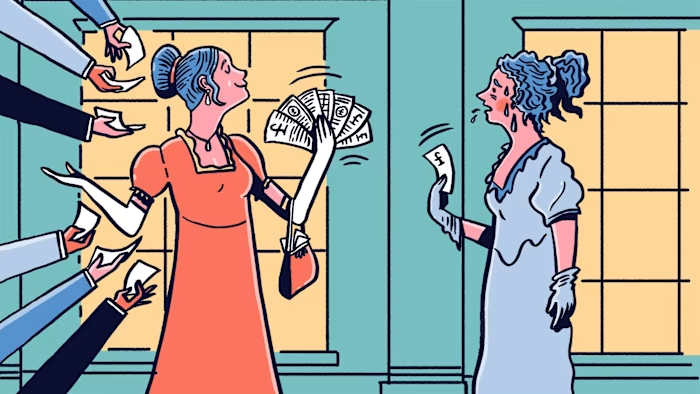
The theme has deep roots in the UK. The rural gentry in Jane Austen’s novels subsisted on yields from land, shares and bonds. If you rewrote Sense and Sensibility as a financial thriller, prudent Elinor would be an income investor. Flighty Marianne would be in doomed pursuit of capital gains from the latest hot theme.
“Fie, sir!” she would tell an unwanted suitor, as they whirled round a ballroom, “I perceive you are a tradfi nocoiner! Yet I have filled my boots with meme stocks and bitcoin!”
Income remains an evergreen theme for UK private investors, including some readers of this column. Indeed, mature legacy businesses dominate the UK stock market partly as a result of historic yield-driven investment.
Does the approach still make sense? That question bothers me as an erstwhile investor in UK income funds, now heavily exposed to foreign trackers propelled by capital growth.
Purist income investment is appealing for two main reasons. First, it provides a sense of security. If you do not touch your capital, its yields should support you for as long as required. Second, it is administratively tidy. Your stocks, bonds or funds will produce regular payments. You need not dither over what proportion of any capital gains to withdraw for living expenses.
But there have been big negatives in recent years. The biggest has been opportunity cost. Global equity returns have been driven by US tech stocks. These have made massive capital gains. Their dividends have been either modest or non-existent.
The dividend yields on equity indices look unimpressive at a time when government bond yields are around 5 per cent. “The idea of leaving your capital untouched and living on dividends is highly attractive on paper,” says Dan Coatsworth, head of markets at investment platform AJ Bell. “But 3 per cent is plainly not enough.”
A chart illustrates the problem. This also shows how crazy it would be to focus on percentage paybacks in isolation. If you do so, the dividend yield on the FTSE 100 appears reassuringly stable at 3 per cent to 4.5 per cent since 2021. In reality, cash payouts have been as volatile as the share prices on which yields are calculated.
Those gyrations would make household budgeting tricky if dividends were your sole source of income, for example as a retiree. A chunky fund would be required, moreover: some £1.2mn yielding 4.5 per cent annually to hit the post-tax “comfortable” retirement living standard of £45,000 a year specified by Pensions UK.
Share buybacks, which generate no income for long-term shareholders, have meanwhile gained ground against dividends as a way for companies to reward investors. Unlike dividends, buybacks generate no income tax charge for continuing investors, who chalk up a pleasing paper gain on their shareholdings.

In common with some other pundits, I used to inveigh against buybacks. I stopped when I realised I sounded like a snooty film critic telling cinemagoers they were wrong to enjoy Bohemian Rhapsody or Mamma Mia! No one cared.
For the reasons mentioned, investors have been heavy sellers of UK income funds for several years. Global equity funds, with their superior growth prospects, have done better. The broader picture is of net sales of retail funds, according to Investment Association numbers.

Does my list of negatives mean income investment is obsolete? My feeling is that it still has a role to play in personal investment. It represents a useful diversification, even though it has lost its mojo as an all-encompassing solution.
If you allocate a chunk of your portfolio to income investment, what should you buy? Most investors would define income stocks as bearing dividend yields of 3.5 per cent to 7 per cent. UK-focused financial services groups are among the steady payers.
Above 7 per cent, danger may lurk. “A high yield can lead you into a value trap,” warns Marty Connaghan, senior investment director at Aberdeen Investments. “The company may be about to cut its dividend.” The share price may have already fallen in anticipation.
Connaghan recommends checking two other metrics to assess payout sustainability. The first is dividend cover. This is usually deemed acceptable when earnings per share comfortably exceed dividends per share (DPS). The second test is that free cash flow per share is greater than DPS. Free cash flow strips out most of the non-cash items that can distort reported earnings.
What about fixed-income bonds, perhaps the most obvious income asset class? Here, payouts are pretty much guaranteed unless the issuer defaults. They are as steep as 7 per cent for better-quality high-yield bonds, says Jack Holmes, a fund manager at Artemis. The colloquial designation of “junk” is discouraging. “But quite a lot needs to go wrong for you to miss out on that 7 per cent,” Holmes says.
That aside, living on investment income alone no longer constitutes a financial strategy for most better-off Britons.
In contrast, Jane Austen’s books never go out of fashion. Recently, I heard news of a brilliant musician I last ran into more than 40 years ago. Back then, friends confidently expected him to become a rock star.
He is still in a band, I discovered, but as a fiddler, not a guitarist. He now plays period-appropriate music at dances for Austen fans dressed in Georgian costumes.
Jonathan Guthrie is a journalist, adviser and author of ‘The Truth About Investing’; [email protected]
